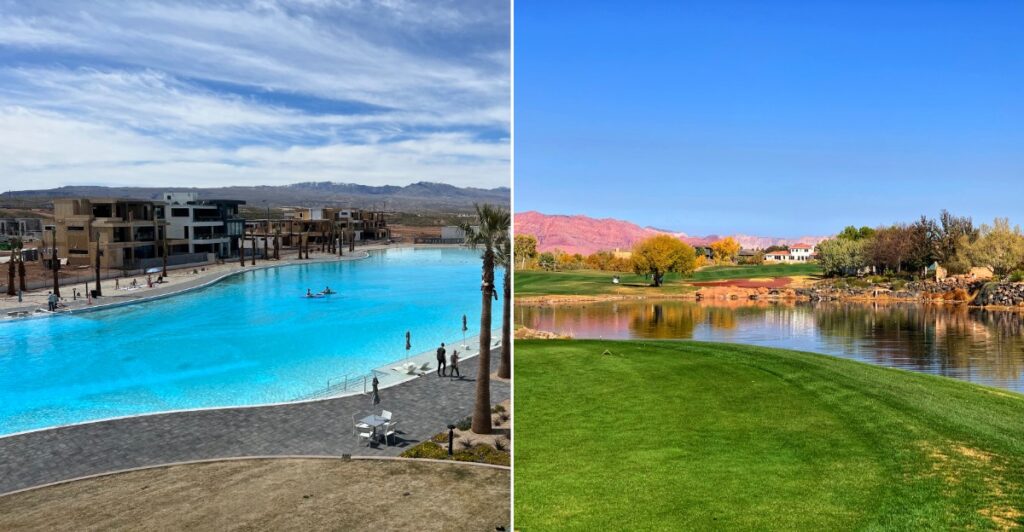
Retirement brochures love scenery. Monthly budgets are much less sentimental.
In St. George, the red rock backdrop and mild winters can look inviting, but housing costs have become a serious part of the conversation for people living on fixed or slowly changing incomes. That tension matters across southern Utah, where a beautiful setting does not automatically translate into an easy financial fit.
The real question is not whether the area is appealing. It is whether the numbers still work after housing, utilities, taxes, insurance, and everyday expenses join the picture.
Prospective retirees can protect themselves by comparing total monthly costs, checking neighborhood differences, and leaving room for increases over time. A move should feel exciting, not like a spreadsheet ambush.
For anyone considering this corner of Utah, the smartest preparation starts before the boxes do, with a clear budget and a realistic look at what retirement will cost each month.
Housing Takes A Bigger Bite In St. George
A retirement budget can look comfortable until the housing line gets its turn. In St. George, Utah, someone choosing between a house, condo, or rental needs to compare the full monthly cost, not just the price in a listing.
A lower payment on paper may leave out taxes, insurance, upkeep, or community fees.
Housing matters so much because most other spending can change from month to month. You might eat at home more often or put off a purchase.
Rent or a mortgage payment is less flexible. For retirees living mainly on savings, Social Security, or a pension, that difference can shape nearly every other choice.
Start with a number you can pay without using money set aside for medical care or emergencies. Then add the bills that come with the kind of home you want.
Ask what happens if insurance or fees rise, and leave room for repairs even in a newer house. St. George still has its outdoor appeal, but a view is easier to enjoy when the budget beneath it holds up.
Choosing a smaller home can help, though only if its total costs truly come out lower over time.
Downsizing Can Come With New Bills
Trading a large house for a smaller one sounds like simple math. Fewer rooms should mean fewer costs, right?
Not always. In St. George, a condo or a home in a planned community may reduce yard work while adding monthly association dues.
Those dues can cover useful services, but they still need a place in the budget.
Before buying, ask what the fee pays for and which jobs remain yours. Roof care, landscaping, shared spaces, and building insurance may be handled in different ways.
Read the rules, too. A home that looks affordable can become less appealing if future fee increases would squeeze the money available for groceries, travel, or care.
Selling a longtime home also has costs. Moving, closing expenses, and getting a new place ready can use more cash than expected.
Write those costs down before treating sale proceeds as spending money. If you plan to rent after selling, compare several realistic rents with the amount you would keep from the sale.
Downsizing can be a smart move, but the goal is lower total spending and a home that fits daily life, not simply a smaller floor plan. The tape measure cannot answer every money question on its own.
Renting Changes The Retirement Math
A lease can offer freedom from many repair jobs, which sounds pretty good when the weekend plan does not include fixing a sink. Yet rent has its own uncertainty.
A retiree in St. George who signs a lease today may face a different price when it is time to renew. That makes next year’s budget harder to pin down.
Look beyond the advertised monthly rent. Ask about deposits, utilities, parking, and any fees that would come with the unit.
Check which costs the lease says may change. If you are comparing apartments, use the same list for each one; otherwise, the cheapest headline price can win for the wrong reason.
Renters also need a moving fund. Even without plans to leave, keeping enough cash for a deposit and moving costs gives you more choices if a lease becomes too expensive.
Someone considering a move to St. George could rent first to learn which home and monthly payment suit them. That can be useful, but do not assume a short lease will stay affordable later.
A simple test is to ask whether the budget could handle a rent increase while still leaving money for health needs and ordinary surprises.
The House Payment Is Not The Whole Cost
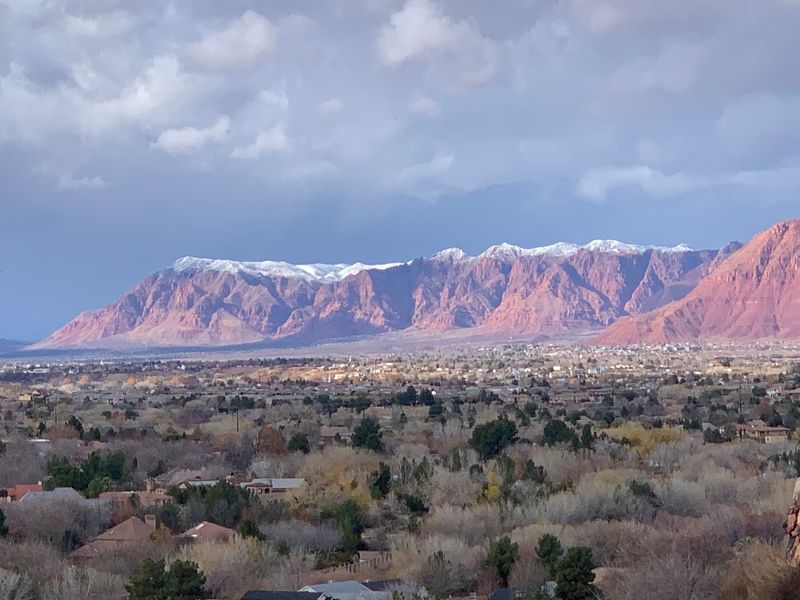
The number that gets the most attention is usually the mortgage or rent. The quieter bills deserve a seat at the table.
Homeowners in St. George also need to plan for property taxes, insurance, utilities, and repairs. A paid off house can still cost a fair amount each month.
Southern Utah’s warm summers make cooling an important part of a household budget. Ask for past utility bills when possible, and remember that one mild month will not tell the whole story.
Insurance deserves the same careful look. The price and coverage of a policy can change, so get a quote for the specific home rather than guessing from a friend’s bill.
Good To Know: A home budget works better when it includes money for the expenses that do not arrive every month. Set aside a little for repairs, service visits, and items that eventually need replacing.
If you are buying, have the home’s condition checked and read what the insurance policy covers. If you already own, review your spending once a year instead of waiting for a large bill to make the point for you.
The aim is not to worry about every faucet. It is to give ordinary household surprises a line of their own.
A Fixed Income Needs Some Breathing Room
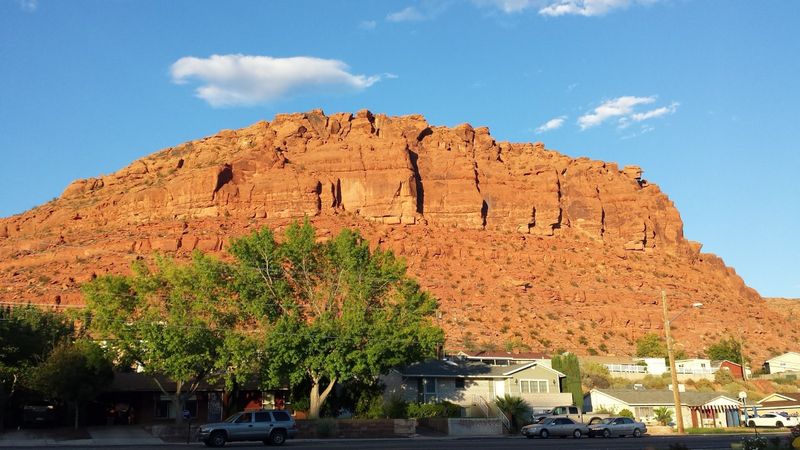
When paychecks stop, rising bills feel different. Many retirees have income from Social Security, pensions, or savings, and each source follows its own rules.
Some payments may grow over time, while others may not. Housing costs can rise anyway.
That gap is why a budget that worked when someone moved to St. George may need another look a few years later.
Put regular income and necessary spending on one page. Start with housing, food, transportation, and health needs.
Then add the things that make retirement enjoyable, whether that means seeing family or taking a quiet day out. The point is not to cut every pleasure.
It is to know which expenses could change if housing takes more money.
Families may find this useful when talking with older relatives about a move. Couples can compare what their finances would look like on one income.
A person living alone may want an even larger cash cushion, since there is no second household income to help with an unexpected bill. These are personal decisions, not a single rule for everyone in Utah.
If the numbers feel tight, a qualified financial counselor can help test several housing choices before a deposit or purchase makes the decision harder to change.
Compare A Move With Staying Put
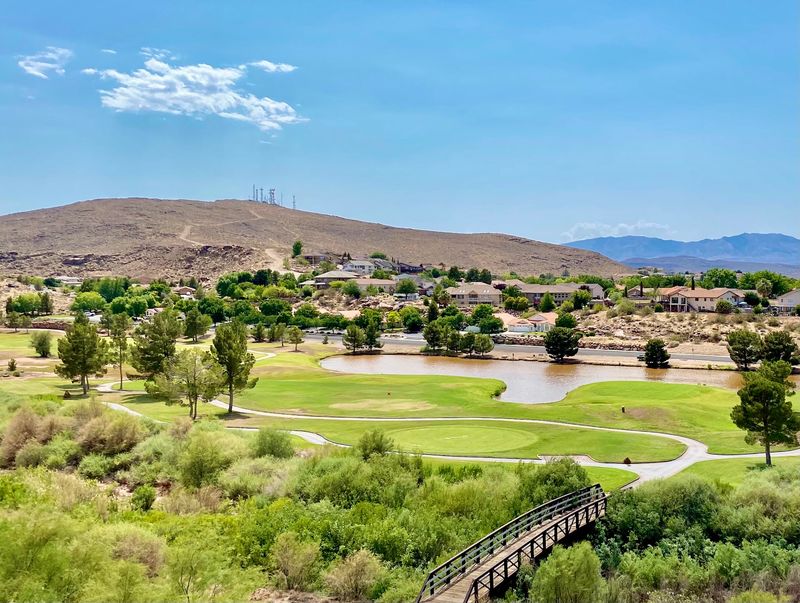
A change of address can promise less work, a different home, or more time near the places you enjoy. It can also trade a familiar set of bills for ones you have not lived with yet.
Before moving to St. George, compare your current housing costs with a complete estimate for the home you are considering.
Use a year’s worth of present bills as the starting point. Include costs that are easy to forget, such as repairs, insurance, taxes, and utilities.
For the possible new home, request actual details where you can. Ask about association dues if they apply.
If you would rent, read the lease terms rather than relying only on an online listing.
Then add the cost of making the move itself. Packing, transportation, deposits, and setting up a home all use money that could otherwise stay in savings.
A quick stop while already in St. George can help you look at an area, but one visit cannot settle a long term budget. Take the numbers home and give them a second look.
You may still decide to move, or you may find that staying put offers more freedom than expected. Either answer is useful when it comes from your own costs instead of a sunny photograph.
Keep The Red Rocks And The Budget In View
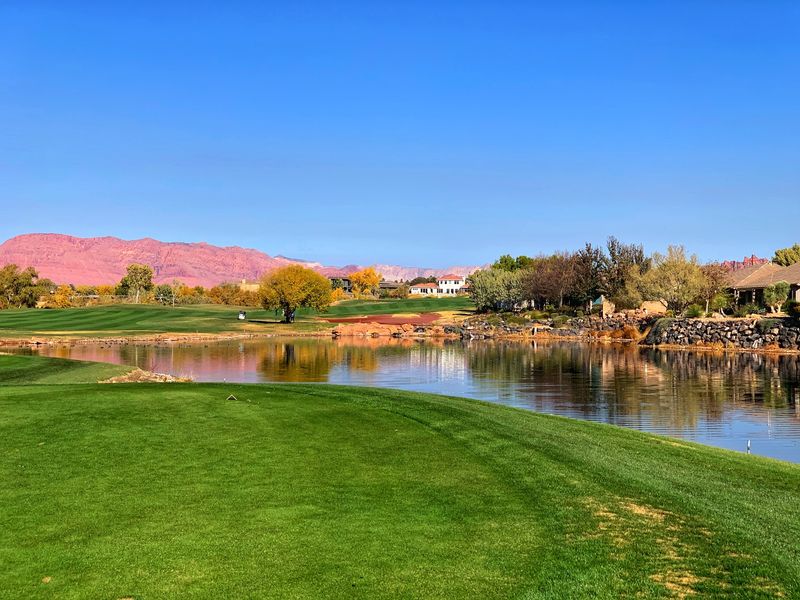
St. George offers a setting that is easy to picture in retirement plans. Red rock scenery and access to outdoor activities give the city a clear draw.
The less exciting part of the picture is a stack of housing bills, and that part deserves just as much attention.
There is no one housing choice that works for every retiree. An owner with a paid off home faces different costs from someone renewing a lease.
A condo may reduce chores but bring association dues. A move may make daily life simpler while using savings at the start.
Looking at the whole cost, rather than a single monthly payment, helps each person see those tradeoffs clearly.
Keep a current list of expenses and check it when a major bill changes. If you are considering St. George, Utah, build your estimate around a specific home and your own needs, not a general promise that retirement will cost less somewhere new.
Leave space for care, repairs, and the ordinary pleasures you retired to enjoy. A budget is not the most interesting thing to bring along when exploring a red rock city.
It might, however, be the reason the view remains relaxing after the first month’s bills arrive. Bring your numbers along with your plans for St. George.